
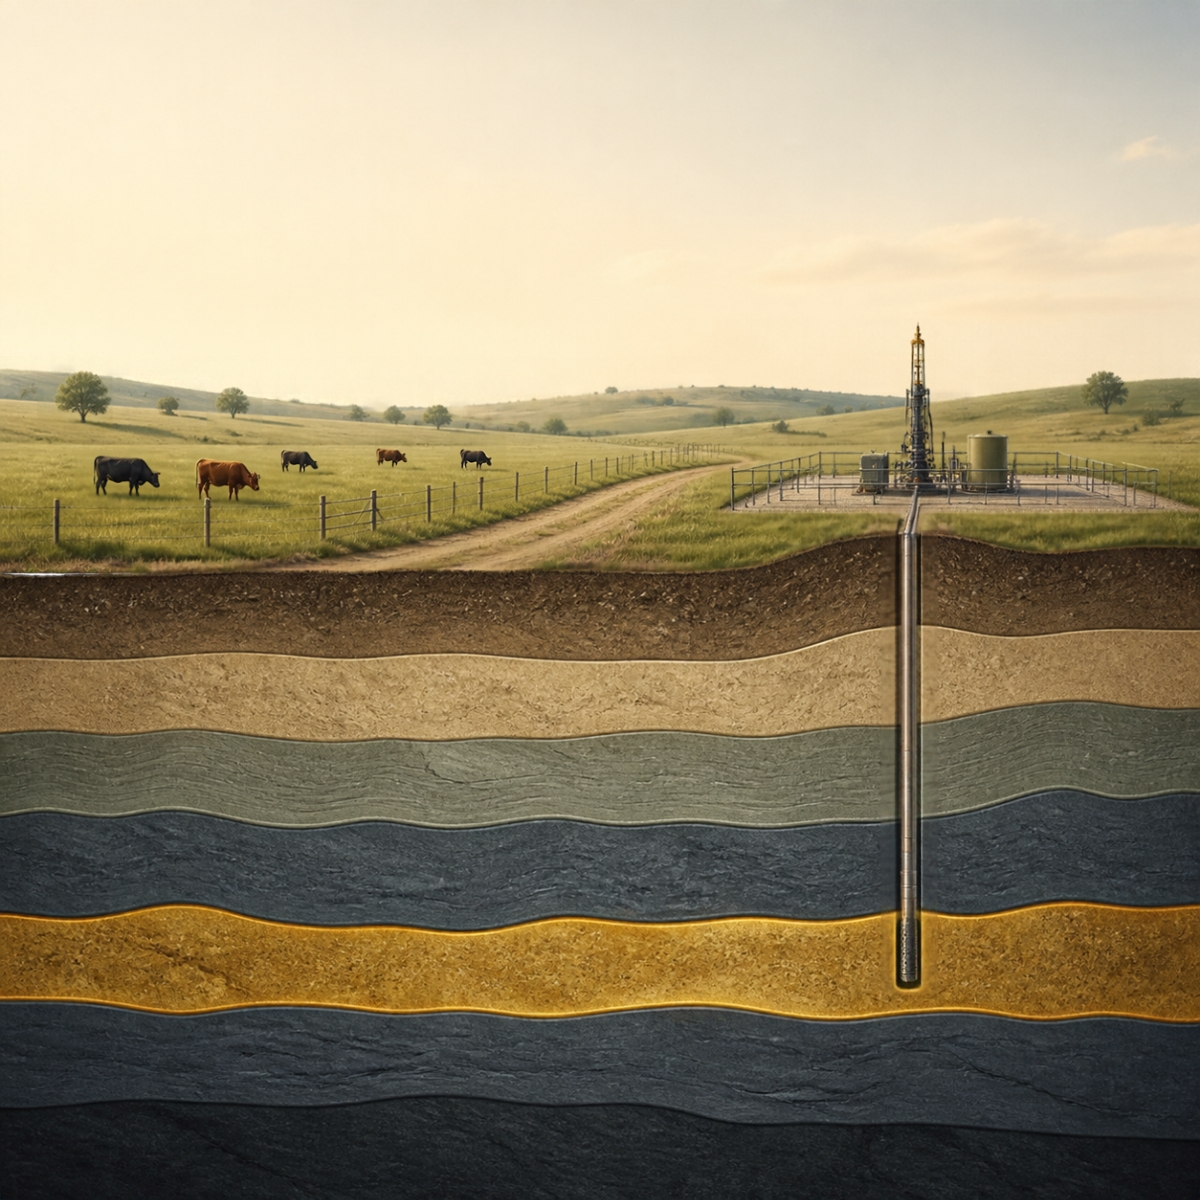
The PPM promises a “100% working interest in 1,280 acres.” An investor pictures two square miles of oil field. In reality, the fund will develop only certain depths beneath that acreage, keep roughly three-quarters of what it produces, cross a rancher’s pasture to reach the wellsite, and hold the lease only as long as the wells keep producing. Nothing in that sentence was false, but it was not the whole picture.
Our last installment covered how to read the offering documents. In “No Tricks, Just Treats,” we explained how the type of asset a fund holds shapes its risk. This installment goes one level deeper, into the property rights themselves: what the fund actually owns, and whether it can use it.
Percentages Are Not Ownership: Working Interest, New Revenue & Net Acres
A working interest is a share of the costs. A net revenue interest is a share of the money. The gap between them is every royalty and overriding royalty stacked on the lease. A 100% working interest under a lease carrying a 25% royalty and a 2% override delivers a 73% net revenue interest, and that is the number that drives distributions. Acreage works the same way: 1,280 gross acres held at a 50% interest is 640 net acres. That 50% can come from the fund’s share of the working interest or from a lease that covers only half the minerals, and the PPM should say which. If the PPM gives you only the larger figure, ask for the smaller one.
Leases Expire: Primary Terms, Prodution & Depth
A lease in its primary term must be drilled or extended before it lapses. A lease past its primary term generally survives only while it produces, and a stretch without production can end it unless a savings clause, such as a shut-in royalty provision, keeps it alive. Many leases also contain Pugh or retained-acreage clauses that release undeveloped depths or acreage outside a producing unit, so the interest that looks broad today can shrink on a schedule written years ago. Ask for the lease schedule with expiration dates and the wells holding each lease. Then compare it with the development timeline in the PPM.
Someone Else Owns the Surface: Surface Rights, Easements & Access
Mineral and surface ownership are often split. In many producing states, the mineral owner may make reasonable use of the surface, but that right has limits, and surface use agreements, damage statutes, and accommodation duties can narrow it. Roads, pipelines, water, and disposal usually depend on easements, and an easement helps the fund only if it is recorded, assignable, and broad enough for the planned use. Newer rights matter too. Several states assign pore space, now valuable for carbon storage, to the surface owner rather than the mineral owner. In 2025, the Texas Supreme Court held that subsurface storage space generally belongs to the surface owner unless an agreement says otherwise.
A PPM does not need to attach every lease, but every headline number should hold up against the record title, from the original lease through each recorded assignment to the fund. Even when title checks out, ownership is only half the analysis. Our final installment asks whether those rights have been kept in good standing.
At RR&A, we read leases, assignments, and title opinions alongside the PPM. If you cannot tell from the offering what the fund actually owns, send us the property description, and we will help you understand what you are buying and how to protect your investment.
Disclaimer: The information and material on this website is general information about our practice and firm. This information does not offer specific legal advice and the use of this information does not create an attorney-client relationship with RR&A or any of its attorneys. The information on this website should not be used for legal advice, and persons should not act upon the information on this website without engaging professional legal counsel.
Miranda is Managing Associate and Team Lead of the Corporate practice area at R. Reese & Associates. To learn more about Miranda, visit her attorney page.