
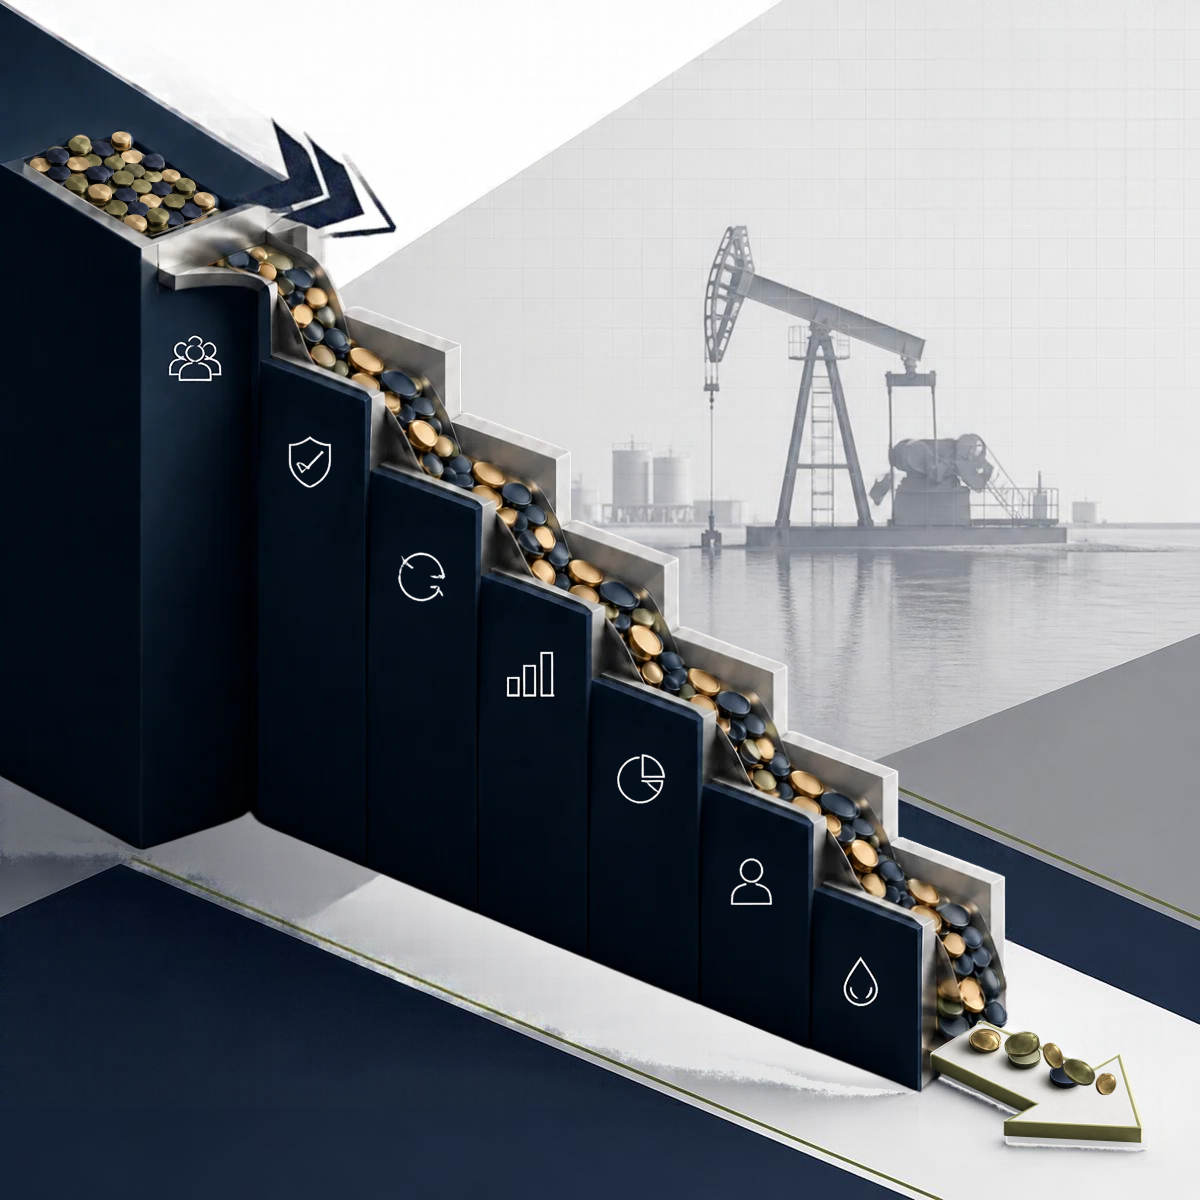
The first distribution goes out, and an investor calls, confused: the check is smaller than expected, and the sponsor’s promote appears to have kicked in earlier than the investor thought the waterfall allowed. Both sides pull out the PPM. The provisions are technically there, but they were written in a way that let two reasonable readers land on two different answers. That gap, between what the PPM says and what an investor understood it to say, is where disputes are born, and it is entirely avoidable. Investors rarely read a PPM cover to cover before investing, but they read the money pages closely: what it costs to get in, who gets paid first, how much, and when. Get those provisions right, specific and matched to how the deal actually works, and a sponsor protects itself as much as it informs the investor.
Capital In: Calls, Use of Proceeds & Fees
Capital calls should be described the way the sponsor actually intends to run them, not as boilerplate. State how and when calls will be issued, what happens if an investor fails to fund one, and what remedy applies to a default, dilution, forfeiture, or a priority return to those who did fund. A program calling capital in tranches tied to drilling milestones needs different language than one that calls it all at closing.
Use of proceeds should track the real plan for the money with enough granularity that an investor can see what goes into the ground, drilling, completion, acquisition, and leasehold, and what goes to the sponsor, fees, offering costs, and reimbursements. Lump it all into broad categories, and investors lose any real ability to judge how efficiently their capital is being deployed.
Management fees deserve the same precision. State how the fee is calculated (committed capital, invested capital, or net asset value), when it is charged, and whether it changes over the fund’s life. If the sponsor also earns fees for operating wells or marketing production, disclose those separately, so an investor can see the sponsor’s full economic take, not just the headline number.
Splitting the Pie: Carried Interest, Preferred Returns & Hurdles
The carried interest, or promote, is usually the most negotiated term in the deal, and the most under-disclosed. State the promote percentage, exactly where in the waterfall it kicks in, and whether a preferred return or hurdle has to be cleared first. “Customary” and “market” are not disclosures; they invite disputes when distributions don’t match expectations. In mineral-focused programs especially, some sponsors are dropping the traditional preferred return altogether in favor of a simpler return-of-capital-then-split structure, reflecting how much longer and less predictable these hold periods can be. Whatever the structure, spell it out. Do not make investors reverse-engineer it from defined terms.
Where a preferred return applies, state the rate, whether it compounds, and exactly how it interacts with return of capital, before, after, or alongside it. If an IRR or MOIC hurdle steps up the promote, define it precisely, including how and over what period it is calculated. A percentage-point difference in how IRR is computed can materially swing outcomes. Because production timing on pre-development assets is often uncertain, some sponsors now lead with a MOIC target instead, since it cares less about exactly when the money arrives. A PPM that discloses only an IRR hurdle, with no explanation of the timing assumptions behind it, understates how much the real return depends on when the asset performs, not just whether it does.
Money Out: Distributions, Returns of Capital & Reinvestment
Walk the waterfall tier by tier, in the order it will actually run, return of capital, preferred return, promote, and say how often distributions are expected given the program’s cash flow. Describe it only in the abstract, and investors cannot model their own returns even if every number is technically disclosed somewhere in the document.
Drilling programs need to address costs specifically: how intangible drilling costs are allocated, how AFE overruns are handled, and who pays when an AFE runs over budget. If the sponsor can reinvest distributable cash instead of paying it out, say so, and say what limits apply, because that discretion directly delays, and can shrink, what investors ultimately see.
The Exit: Monetization & Realistic Expectations
Every economic term eventually answers the same question: how does the investor get out. Describe the anticipated path, continued production and distribution, a sale of the assets, or another liquidity event, and be honest that energy assets are illiquid and no exit is guaranteed on any timeline. Attractive economics on paper are only as good as the exit assumptions underneath them.
Strategy and economics are two sides of the same disclosure. A waterfall walked through step by step, a fee structure stated in real numbers, and an exit honestly framed give investors the ability to underwrite the deal on its actual terms, not on borrowed assumptions from someone else’s fund. At RR&A, we translate deal economics into precise PPM language. Before your next raise, walk us through your waterfall, we will tell you where an investor could read it differently than you intend.
Disclaimer: The information and material on this website is general information about our practice and firm. This information does not offer specific legal advice and the use of this information does not create an attorney-client relationship with RR&A or any of its attorneys. The information on this website should not be used for legal advice, and persons should not act upon the information on this website without engaging professional legal counsel.
Miranda is a Managing Associate at R. Reese & Associates and Team Lead of the Corporate practice. To learn more about Miranda, visit her attorney page.